All Categories
Featured
Securing Affordable Final Expense Insurance in Laguna Hills
Essential Strategies on 2026 Medicare Part D Enrollment

What Veterans in Your Area Should Know About Insurance
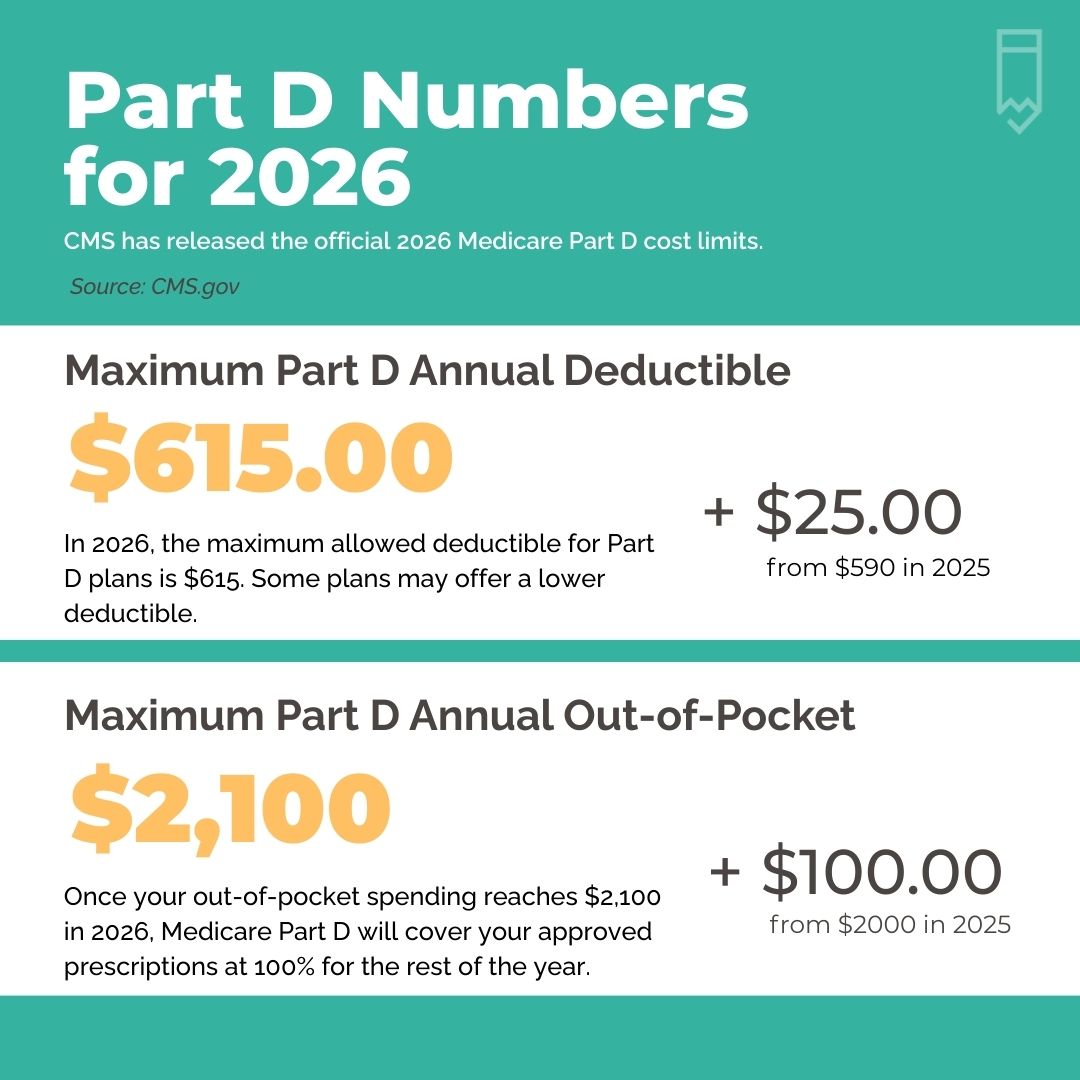
Essential Strategies on 2026 Medicare Part D Enrollment
It's essential to understand how IUL policies work, given that they're more intricate than basic irreversible life policies. An indexed universal life policy is a type of irreversible life insurance, offering long-lasting coverage and a death benefit. The crucial distinction between IUL policies and other types of universal life insurance coverage is how the cash value is invested.
The survivor benefit is the quantity of money your beneficiary gets after you die. With IUL policies, the survivor benefit may be decreased by the quantity of any cash value withdrawals or money worth loans you secured however didn't pay back. This survivor benefit is usually not taxable for your beneficiaries. They both use coverage for life and come with a survivor benefit and cash worth part that grows gradually. However entire life supplies more predictability since the premiums and death benefit remain the exact same, and your cash value grows at a set rate that won't decline. You may have lower premiums with fewer costs compared to an IUL, though you can't change
Choosing the Best Medicare Supplement Plan
premiums or manage the money value financial investment. The floor on the indexed portion of your cash value secures versus market swings. And because the policy isn't straight invested in the stock market, your danger is minimized. You have the option of adjusting your premiums and death advantage while the policy is in force. You can also allocate your cash value to various sub-accounts and possibly select where the indexed account invests. Your recipients also receive a survivor benefit that isn't normally based on income or estate taxes. You may withdraw or obtain from your money worth anytime without penalty. IUL policies don't restrict how much you can contribute each year, enabling you to experience more development if you want to contribute more. Caps and optimal involvement rates limit the quantity of interest you can make in your indexed account. Your insurance provider does not directly invest in stocks, so you will not gain from dividends paid to investors. Insurance provider charge fees for handling your account, which can consume into your money worth. If you withdraw money that includes investmentgains before your policy grows, you might require to pay earnings taxes on the funds. The expense of an indexed universal life insurance coverage policy varies, depending on aspects like your age, where you live, your health and the protection amount you choose. But generally, indexed universal life insurance policies cost more than term life insurance coverage because they consist of a cash value account and neverexpire. For instance, according to one quote, a healthy, nonsmoking 34-year-old lady may pay in between$71 and $96 a month for an indexed universal life policy, assuming$250,000 of coverage. The very same person may pay$32 to$44 a month for a term life policy and in between $177 and$245 each month for an entire life policy.
Insurance in Irvine CAThe death benefit is the quantity of money your recipient gets after you die. With IUL policies, the survivor benefit might be minimized by the amount of any money value withdrawals or money value loans you secured however didn't repay. This death advantage is usually not taxable for your heirs. They both use protection for life and include a survivor benefit and money worth component that grows with time. But whole life supplies more predictability because the premiums and death benefit stay the very same, and your cash value grows at a set rate that won't decline. You might have lower premiums with less fees compared to an IUL, though you can't adjust
Insurance in Irvine CApremiums or manage the cash value financial investment. The flooring on the indexed portion of your money value safeguards versus market swings. And because the policy isn't straight invested in the stock exchange, your threat is decreased. You have the alternative of adjusting your premiums and survivor benefit while the policy is in force. You can also assign your money value to various sub-accounts and possibly pick where the indexed account invests. Your recipients likewise get a death benefit that isn't usually based on earnings or estate taxes. You might withdraw or borrow from your money worth anytime without charge. IUL policies do not restrict just how much you can contribute each year, enabling you to experience more development if you wish to contribute more. Caps and maximum participation rates restrict the amount of interest you can make in your indexed account. Your insurer does not straight buy stocks, so you will not take advantage of dividends paid to investors. Insurance business charge costs for handling your account, which can eat into your money value. If you withdraw money that consists of investmentgains before your policy grows, you may require to pay earnings taxes on the funds. The expense of an indexed universal life insurance policy differs, depending on aspects like your age, where you live, your health and the protection amount you select. Generally, indexed universal life insurance policies cost more than term life insurance coverage because they include a money value account and never everend. According to one quote, a healthy, nonsmoking 34-year-old lady might pay in between$71 and $96 a month for an indexed universal life policy, presuming$250,000 of protection. The exact same individual might pay$32 to$44 a month for a term life policy and between $177 and$245 monthly for an entire life policy.

Latest Posts
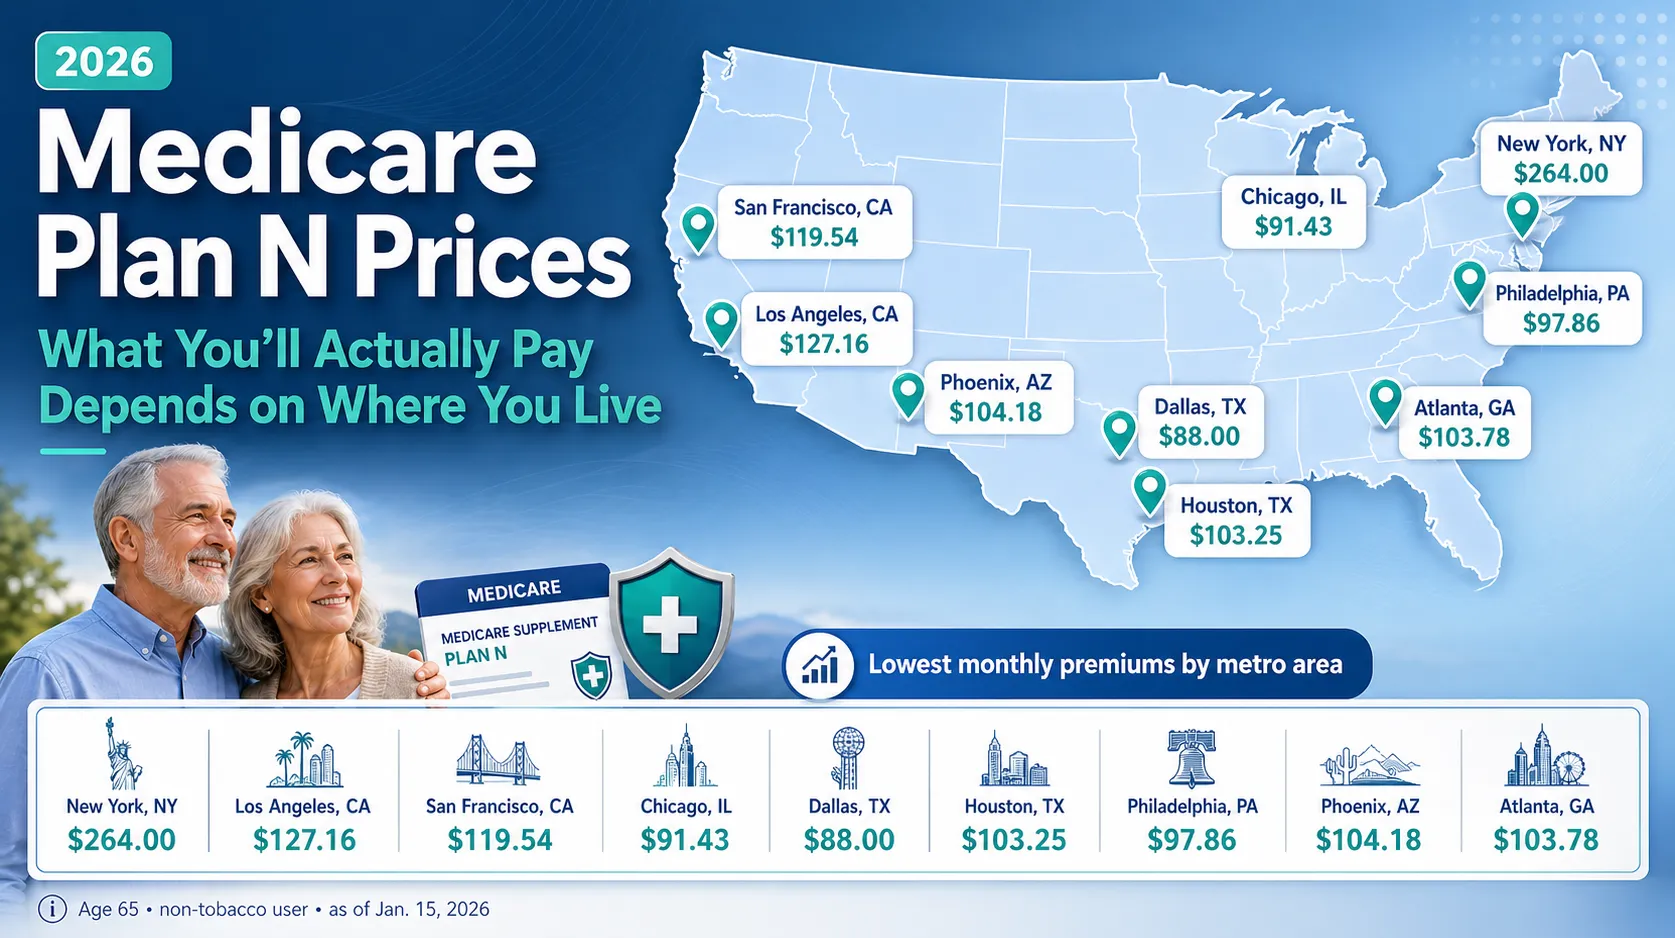
Securing Affordable Final Expense Insurance in Laguna Hills
Essential Strategies on 2026 Medicare Part D Enrollment
How to Optimize Your Medicare